


Group CEO’s Report
The preparation of this report provides an opportunity to reflect upon the achievements, challenges and future prospects of this formidable Group. It also provides an opportunity to share our progress and celebrate the efforts of my 20 007 colleagues.
I am pleased to report Super Group’s outstanding results. In the face of unprecedented political and economic volatility, the Group provided its clients with exceptional solutions and delivered a sound return to shareholders.
Group revenue increased by 30.6% to R61.88 billion and EBITDA increased by 20.8% to R8.49 billion. Operating profit increased by 20.7% to R3.95 billion. Profit before tax increased by 18.7% to R2.97 billion. Group HEPS increased by 23.3% to 469.4 cents and EPS increased by 24.9% to 472.9 cents per share. This performance is testimony to a consistent focus on cost management and efficiency. It also reflects the stringent management of cash flows and balance sheet exposures.
TRANSLATING COMPETITIVE EDGE INTO SHAREHOLDER VALUE
The Group’s operations span diverse geographies, industries and currencies, reducing volatility and providing a more stable long-term investment. This diversification is a deliberate strategy to optimise returns while minimising risk. It positions Super Group to leverage emerging trends, adapt to changing market conditions and realise opportunities inherent in volatile markets. The Group’s market-leading technology remains key to realising opportunities in the form of client acquisitions and market share gains.
Technology also serves as the bedrock for unique solutions that go beyond easy replication, empowering our clients with unparalleled visibility, flexibility and insight.
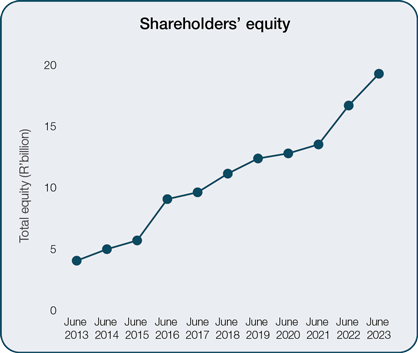
The powerful combination of diversity, technology, scale and experience provide Super Group with a competitive edge that translates into value creation capabilities for shareholders and other stakeholders. Over the past decade, shareholders’ equity has grown from R4.3 billion at June 2013 to R19.5 billion at June 2023, a compound growth rate of 16.4% per annum.
Other key drivers of shareholder value remained equally positive, with the Group’s return on net operating assets (RNOA) improving to 10.2% against a weighted average cost of capital (WACC) of 7.0%. The full-year dividend increased by 27% to 80 cents per share, equating to a cover of 5.9 times. Read more about the Group’s sustainable profitability.
Supply Chain Africa delivered an excellent performance, with revenue increasing by 38.3% to R17.80 billion and operating profit increasing by 48.7% to R1.26 billion. Operating margin increased from 6.6% in the previous year to 7.1% in the current year and profit before tax increased by 44.7% to R1.11 billion.
Technology-based solutions in the consumer businesses delivered greater efficiencies and cost savings to clients, contributing to significant new business wins and contract renewals. A diversified product basket and improving volumes in industries such as hospitality, entertainment and quick service restaurants also contributed to this strong performance.
Strong volume increases were experienced in the South African and African Logistics consumer and commodity transport businesses. The industrial businesses also performed well, with good sales and profit performances from SG Mobility, SG Freight and Super Rent.
OutlookThe trading environment for the South African supply chain businesses will remain a difficult one, characterised by high unemployment rates and rising inflation. Manufacturing and supply chain disruptions, exacerbated by loadshedding, will continue to negatively impact product availability and prices. However, the Supply Chain Africa business remains agile and resilient in the face of this macroeconomic turbulence, and a focus on strategic delivery is expected to result in a strong performance next year.
With innovative technology and market diversification underpinning a robust growth strategy, new business wins and contract renewals should continue to boost revenue growth in the consumer businesses. Further improving volumes in hospitality, entertainment and quick service restaurants are also expected to bolster performance.
Improved commodity prices and volume increases across all commodities should continue to benefit the division, with low inventories and growing export volumes expected to maintain activity levels into 2024.
Read more in Divisional performance.
Supply Chain Europe’s overall performance improved considerably, reflecting the ongoing evolution of the business model to ensure both relevant services and optimised cost structures. Operational enhancements such as the consolidation of shipments onto larger vehicles, higher average kilometres per load, and the recovery of increased diesel and other operating costs have been key to growth.
Ader acquired 75% of the shares in both T.I. and Delver in the north of Spain on 1 July 2022. These businesses provide last-mile distribution services, primarily within the temperature-controlled environment. Revenue from these acquisitions amounted to R366.0 million for the year.
inTime’s average turnover per transport increased by 22.8%, including an 8.8% increase in kilometres per transport, as a result of consolidating shipments. Overall European revenue increased by 30.0%, with inTime’s revenue increasing by 21.4%, Ader’s by 38.5% (including the acquisitions) and TLT’s by 38.8%. Operating margin for the division increased from 1.9% to 2.7%, driving an operating profit growth of 84.1%.
Although off a small base, LiBCycle’s revenue increased fourteenfold, delivering its first profits since inception in October 2021. The innovative business provides a comprehensive solution to the automotive sector in Europe for the transportation and storage of lithium-ion batteries.
The weakening of the average Rand against the Euro had a minimal impact.
OutlookA gradual improvement in the availability of new vehicles and automotive parts volumes should bolster the performance of the European supply chain business. The division will maintain its focus on industry diversification, with further expansion expected in the agricultural and industrial parts sectors. Rigorous cost management remains essential.
Read more in Divisional performance.
SG Fleet’s performance benefited from continued strong order growth, better supply levels and a more supportive labour environment. Customer wins and orders resulted in steady growth, with the order book again outpacing deliveries and further extending order pipelines. Revenue increased by 23.6% to R12.14 billion and operating profit increased by 23.0% to R1.63 billion.
With better vehicle supply largely limited to new market entrants and EV manufacturers, and mainstream vehicle models remaining scarce, used vehicle values remained stable and elevated. As disposal volumes improved in line with higher delivery numbers, this continued to benefit the business.
The LeasePlan integration progressed well, with a focus on further benefit extraction by standardising SG Fleet’s offering across the two brands and leveraging its greater scale. Improved supply arrangements were obtained for tyres, accident management and roadside assistance, in addition to earlier fuel renegotiations. These initiatives translated into successful customer retention and increasing product penetration.
The weakening of the average Rand against the AUD positively impacted the results by R88.2 million for the year under review.
OutlookSG Fleet is expected to perform well, with the steady improvement in the availability of new vehicles helping to meet pent-up demand. This improvement in availability will partially moderate the pricing of used vehicles. New business wins, strong retention rates and the realisation of the LeasePlan synergies will support sustainable growth.
Read more in Divisional performance.
Fleet Africa reported solid results, with good growth in ad hoc rental volumes on existing contracts. Revenue grew by 1.2% to R1.09 billion and operating profit by 8.2% to R243.1 million. Operating margins grew from 20.9% to 22.3%.
Underpinned by innovative technology, efforts to secure new business outside of the parastatal sector progressed well. Fleet Africa’s joint venture with the
Co-Op Bank in Kenya continued to gain momentum and the region remains a key component of the business’ growth strategy. The Kenyan operations reported revenue growth of 50% and operating profit growth of 39%.
OutlookFleet Africa remains well positioned to withstand a volatile trading environment and leverage the opportunities it presents. Despite a sluggish new business pipeline, increased activity on existing contracts and good growth in ad hoc rental volumes should continue to produce solid results.
Fleet Africa will maintain its focus on growing its private sector customer base and management service offering encompassing funding, maintenance and insurance solutions. Further expansion of the business’ fleet lease presence in East Africa also remains a priority.
Read more in Divisional performance.
The focused execution of a multi-faceted strategy saw Dealerships SA perform well ahead of the National Association of Automobile Manufacturers of South Africa (NAAMSA) sales statistics and deliver strong profit growth.
Revenue increased by 14.5% to R10.60 billion and operating margins from 3.7% to 3.9%. Operating profit increased by 20.7% to R408.3 million, mainly due to a stronger contribution from new vehicle sales and associated services, ongoing cost containment and a good aftermarket parts and service performance.
The business continued to grow its representation of volume/value brands and establish multi-brand facilities, enabling it to meet resilient consumer demand despite ongoing shortages of certain brands and models. Technology remained the foundation of service quality delivery and was key to the customer experience and sales pipeline development.
OutlookWith consumers expected to remain under pressure, the year ahead will be a challenging one for the South African dealership market. Given the impact of inflation and interest rate hikes, consumers will continue to delay their purchase decisions or will look to buy more affordable brands or models. Nevertheless, the business remains well positioned to mitigate this volatile trading environment and leverage the opportunities it presents. The management structure will remain compact and agile, maintaining a lean cost base and effective management of working capital.
Dealerships SA will continue to strategically grow its representation of volume and value brands, with a focus on geographic synergies and multi-brand facilities. Technology will remain key to superior customer experience, service quality and a robust sales pipeline. Supported by strong contributions from services and ancillary products, Dealerships SA is well placed to deliver another good performance.
Read more in Divisional performance.
The Dealerships UK footprint continued to grow as a result of strategic acquisitions in selected brands and key locations. Six dealerships – one Ford, one Suzuki, two Kia and two Hyundai – were added in the first half of the year, with a further Suzuki business added in the second half.
The division performed well in the year under review, reporting a 29.1% increase in profit before tax, despite the pressures of continued inflation and higher interest rates negatively impacting consumer confidence across the United Kingdom.
New vehicle sales volumes increased by 39.9% as availability of stock improved over the second half, which compared favourably with the UK passenger and light commercial vehicle (LCV) market performance of 11.9% over the same period. Used vehicle sales volumes increased by 29.0% as stock availability improved.
The weakening of the average Rand against the GBP positively impacted the results by R13.7 million.
OutlookImproved availability of new vehicle stock will support a good performance, although the consumer remains under financial pressure from interest rates at historic highs. The demand for used vehicles will continue to decline as new vehicles become more readily available, with lower margins being realised as a result. Strong demand for commercial vehicles will support performance in the year ahead.
Read more in Divisional performance.
ENSURING LONG-TERM VALUE CREATION
Balancing environmental initiatives with shareholder interests is crucial for long-term value creation. While pursuing earnings growth and maximising shareholder value are essential objectives, it is equally important to consider the sustainability of our environment and our communities. Super Group has intensified its efforts to identify and address the risks posed by climate change. The Group has developed and implemented robust mitigation strategies, thereby safeguarding its operations and contributing positively to climate challenges.
By placing innovation and sustainability at the core of its operations, Super Group aims to pave the way for a greener, more responsible future. The business has adopted a proactive and practical approach towards environmental concerns. Managing the Group’s carbon footprint, utilising renewable energy, minimising waste generation and supporting water conservation efforts simultaneously protects the environment and realises efficiencies and cost savings. Read more about the Group’s sustainability initiatives.
A business cannot thrive in isolation from the ecosystem in which it operates, and Super Group accordingly strives to build strong community relationships. In 2023, the Group invested R26.4 million in CSI projects and programmes (2022: R21.1 million), addressing the most pressing needs of the people who live and work in the communities we serve. These encompass initiatives to tackle hunger and improve education, healthcare, youth development and job creation, and ensure that Super Group plays a meaningful role in fostering sustainable and inclusive community development. Read more about the Group’s CSI initiatives.
FACING THE FUTURE WITH FOCUS AND OPTIMISM
With the global landscape set to remain volatile, it is undeniable that the Group will face challenges in the year ahead. But while the operating environment may seem daunting, it presents opportunities to innovate and grow market share. Super Group has proven itself to be resilient and adaptable. The Group’s ability to overcome obstacles and seize opportunities has been the cornerstone of our success, and the year ahead will be no different.
Super Group will continue to collaborate with its clients and provide them with solutions that exceed their expectations. This dedication to excellence and innovation will set us apart from competitors.
I extend my appreciation to the Board and my fellow executives for their focus, passion and strategic guidance. In the face of unprecedented challenges, the Group has persevered, evolved and delivered on ambitious financial and operational objectives.
Finally, I extend my gratitude to our valued clients, shareholders, partners and suppliers. Your continuous support has been instrumental in Super Group’s growth and success.
The future holds immense promise for Super Group. We will continue to navigate challenges, seize opportunities and deliver sustainable value for all stakeholders.
Peter Mountford Group CEO
29 September 2023